

What a brutal six months it’s been for Offerpad. The stock has dropped 49.2% and now trades at $3.78, rattling many shareholders. This was partly due to its softer quarterly results and might have investors contemplating their next move.
Is now the time to buy Offerpad, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think Offerpad Will Underperform?
Even with the cheaper entry price, we’re cautious about Offerpad. Here are three reasons why OPAD doesn’t excite us, plus one stock we’d rather own.
1. Decline in Homes Sold Points to Weak Demand
Revenue growth can be broken down into changes in price and volume (for companies like Offerpad, our preferred volume metric is homes sold). While both are important, the latter is the most critical to analyze because prices have a ceiling.
Offerpad’s homes sold came in at 206 in the latest quarter, and over the last two years, averaged 39.2% year-on-year declines. This performance was underwhelming and implies there may be increasing competition or market saturation. It also suggests Offerpad might have to lower prices or invest in product improvements to grow, factors that can hinder near-term profitability. 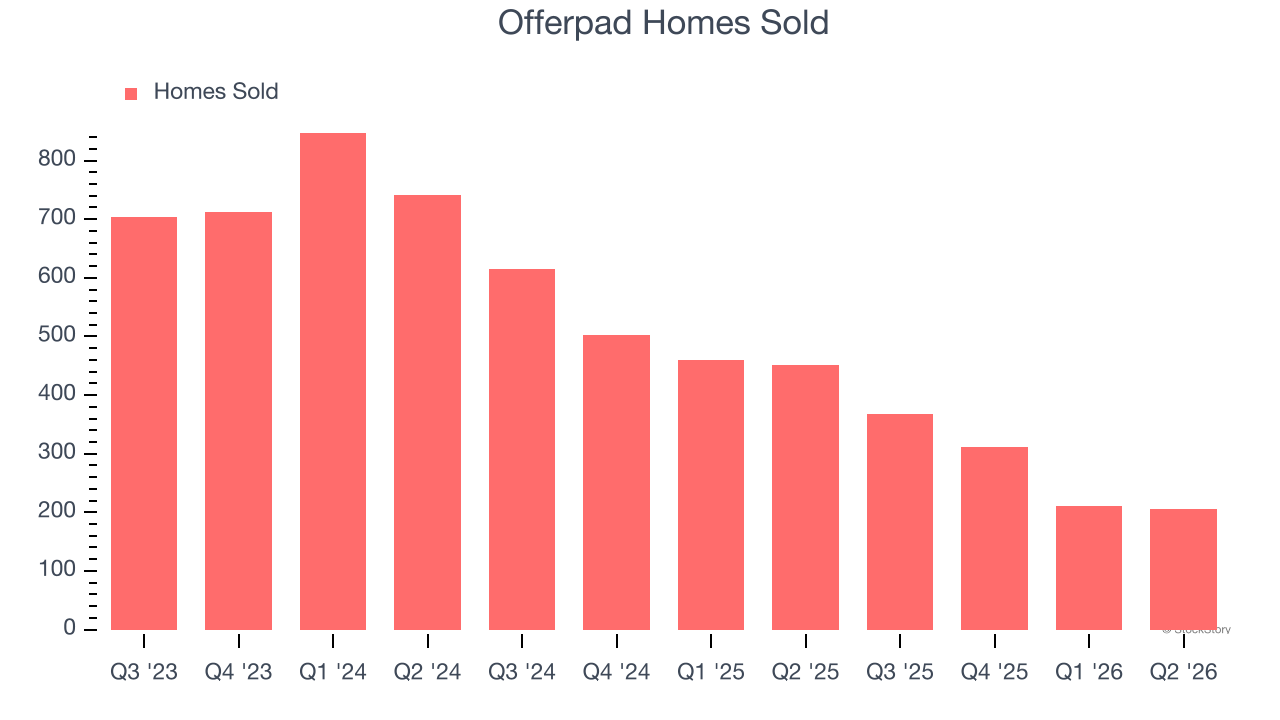
2. New Investments Fail to Bear Fruit as ROIC Declines
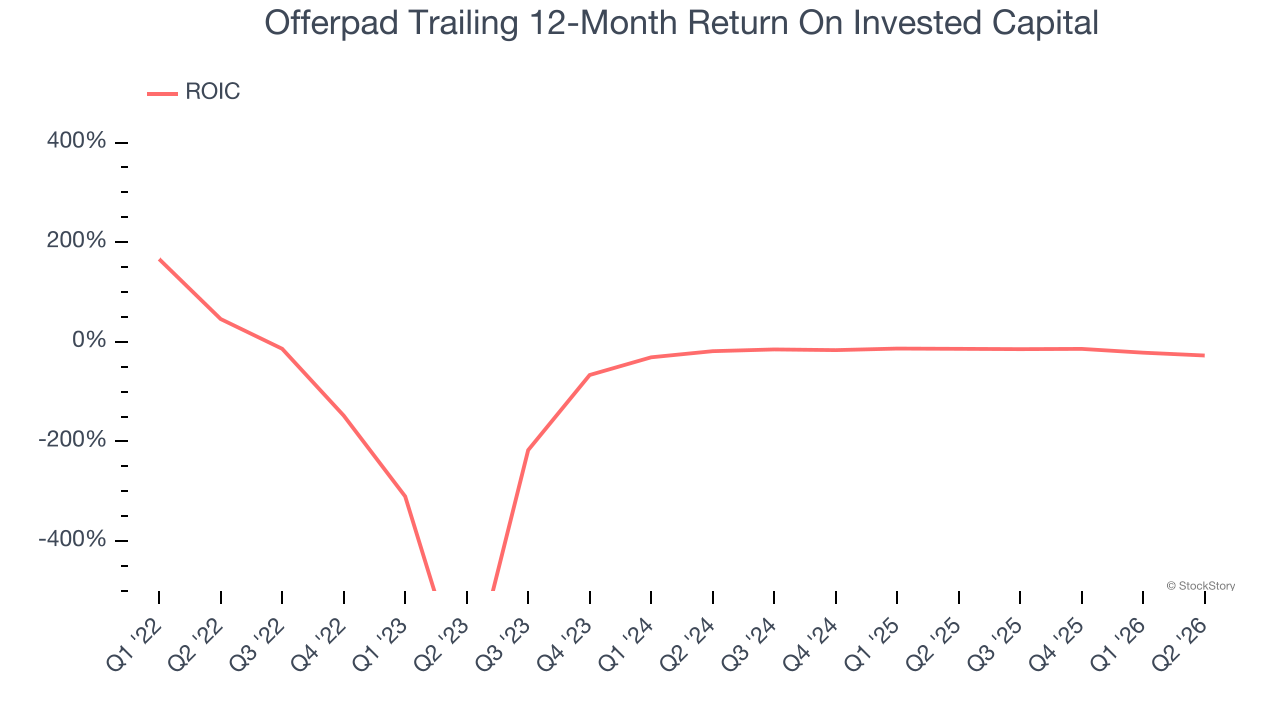
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Unfortunately, Offerpad’s ROIC has decreased significantly over the last few years. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
3. Restricted Access to Capital Increases Risk
Debt is a tool that can boost company returns but presents risks if used irresponsibly. As long-term investors, we aim to avoid companies taking excessive advantage of this instrument because it could lead to insolvency.
Offerpad posted negative $24.39 million of EBITDA over the last 12 months, and its $101 million of debt exceeds the $34.86 million of cash on its balance sheet. This is a deal breaker for us because indebted loss-making companies spell trouble.
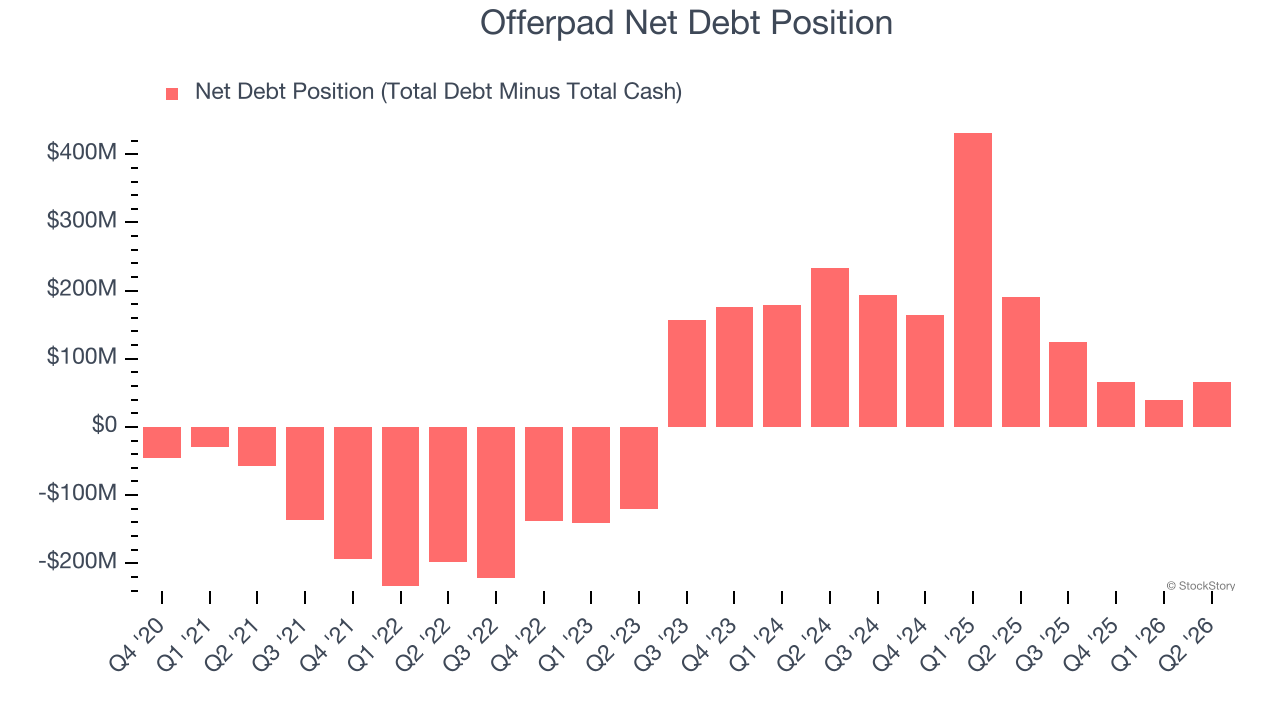
We implore our readers to tread carefully because credit agencies could downgrade Offerpad if its unprofitable ways continue, making incremental borrowing more expensive and restricting growth prospects. The company could also be backed into a corner if the market turns unexpectedly. We hope Offerpad can improve its profitability and remain cautious until then.
Final Judgment
Offerpad doesn’t pass our quality test. After the recent drawdown, the stock trades at $3.78 per share (or a forward price-to-sales ratio of 0×). The market typically values companies like Offerpad based on their anticipated profits for the next 12 months, but it expects the business to lose money. We also think the upside isn’t great compared to the potential downside here - there are more exciting stocks to buy. We’d suggest looking at one of our all-time favorite software stocks.
Stocks We Like More Than Offerpad
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.